The Silicon Curtain

Beyond the Beltway: The Silicon Curtain

On June 23, the European Union, Germany, the Netherlands, and Greece signed onto Pax Silica, a non-binding U.S.-led initiative to build China-free supply chains across the full AI stack, including semiconductors, critical minerals, and compute infrastructure. As China controls an estimated 70% of global critical mineral processing and over 90% of production of key materials used in advanced electronics, the new commitment builds off of Washington’s tightening export controls on advanced AI chips.

The timing is not coincidental. The G7 Summit concluded last week, where AI governance featured at the center of the agenda for the first time. Heads of state met directly with tech executives to coordinate on safety, deployment, and supply chain resilience.

Reading the room:

  • The AI supply chain is no longer commercially neutral. Sourcing decisions, data center locations, and technology partnerships now carry alliance-level implications. The Pax Silica membership list provides a new lens for reading technology supply chain exposure. 

  • Tech sovereignty is the new industrial policy. Governments across North America, the EU, and Asia are moving simultaneously to localize AI capabilities – not just regulate them. For multinationals, this creates compounding pressure: compliance in one jurisdiction may conflict with operational continuity in another. 

  • Non-member status carries its own risk. Companies in countries outside the Pax Silica framework face growing uncertainty on export access, technology partnerships, and capital flows.

For more tailored insights, reach out to geopolitics@fgsglobal.com.
By the Numbers

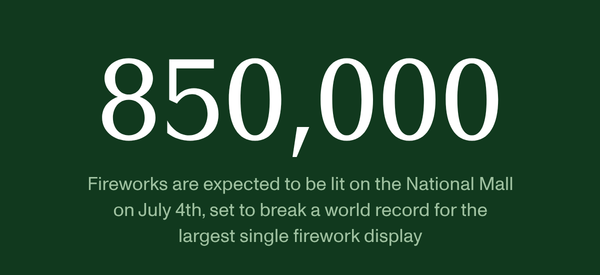
Light text on a dark green background, displaying: "850,000 fireworks are expected to be lit on the National Mall on July 4th, set to break a world record for the largest single firework display."

Game Over

A gaming console with neon blue and red controllers, illuminated against a black background.The AI infrastructure boom is reshaping consumer electronics, and the gaming industry is absorbing some of its sharpest costs. Memory chip prices doubled in the first quarter of 2026 and are forecast to rise another 63% this quarter, as manufacturers redirect capacity toward the high-bandwidth memory that data centers demand.

With the memory crunch expected to last until 2030, gaming companies built on the joy of play are being repriced by the economics of enterprise infrastructure. Nintendo watched its share price fall by nearly a third this year because the chips inside its Switch 2 consoles come from the same suppliers feeding the world’s largest AI data centers. The company is now expecting to absorb an extra ¥100 billion in costs this year. Meanwhile, Sony raised PS5 prices by up to $150 in March. Last week, Microsoft announced its third Xbox price hike since late 2025, after storage and memory costs surged 2.5x, with another doubling forecast by fall 2027.

The traditional console business model – sell hardware at scale, build a player base, and monetize through software – is no longer sustainable. If hardware shifts from a mass-market product to an aspirational one, the consequences ripple outward to third-party developers like Take-Two and Ubisoft, whose economics depend on large installed bases. The future of the gaming industry may rest on pivoting toward lower-tech gameplay, IP licensing, and entertainment crossovers to stay afloat.

For more stories like this, subscribe to FGS Global's Asia in Context newsletter.

Capital Punishment?

City skyline with skyscrapers under a transparent overlay of fluctuating stock market graphs in a blue-toned image.Financial services providers operate in a state of permanent regulatory flux, and the current environment is more complicated than ever. AI adoption, tokenization, the rise of private capital and unregulated non-banks competing for the same customers are all accelerating simultaneously, while the regulatory framework struggles to keep pace. FGS Global's North America Financial Services team has outlined what institutions should be watching:

  • AI integration remains early-stage and unsettled. Regulators have not established clear direction, and given how far development has outpaced oversight, none is likely soon. Institutions building proprietary AI tools are better positioned to manage privacy and cybersecurity concerns than those relying on third-party products.

  • Deregulation has real limits. Banks have gained ground – relaxed international capital standards, lighter supervision, and digital asset permissions under the GENIUS framework – but they remain far better capitalized than pre-2008, even after Basel III was scaled back.

  • Consumer protection is fragmenting. Financial services providers broadly support the near-elimination of the CFPB, but state Attorneys General filling the void are unlikely to replicate the agency's reach or consistency.

  • M&A is slower than expected. The wave of small and mid-sized bank consolidation forecast under the second Trump administration has not materialized, partly due to compliance concerns triggered once institutions cross certain size thresholds.

To learn more, reach out to FIGCommittee-NA@fgsglobal.com.

June 30, 2026
By Nedra Pickler, Irene Moskowitz and Erin Barth-Dwyer

Share

Want to see more of this in your inbox?